Bangladesh’s New Pension System: Where Global Operators Can Engage Today, and What Is Still Unclear
Bangladesh is building a pension system for tens of millions of workers who have none. The rules for private operators are not written yet. Here is where the openings are, and what to watch.
Bangladesh is building a pension system for private-sector and informal workers for the first time. The state-run Universal Pension Scheme (UPS) is now backed by a mandatory-enrolment rule for larger employers, and the government has named a pension fund for private-sector employees as an election commitment. Today the system leaves no direct role for private fund managers. The realistic opportunities for Global Operators are in technical expertise, system and process design, employer-side solutions and, later, partnerships as the framework opens. Timelines are long and policy may shift.
Key points
- The state-run Universal Pension Scheme (UPS) has no direct role for private fund managers today.
- Mandatory enrolment for larger employers and a funded modernisation project are creating real demand for expertise.
- A private-sector pension fund is a government commitment, but its design is unpublished.
- Public trust in the government run scheme is low, and the authority’s own chairman names trust and awareness as the main challenge.
- In contrast, Global Operators enjoy high levels of trust, mainly due to their long experience in managing such schemes, prudent governance and compliacne to strict supervision regulations globally
- Operators who prepare now will be better placed when the framework opens.
Why this market matters
Bangladesh’s labour force is about 77.4 million, and around 85 percent work in the informal sector, outside formal pension and provident fund coverage (BSS, June 2026). The government aims to bring at least one member of each of the country’s 40 million families into the scheme by 2030. By July 2026 the UPS had roughly 400,000 registrants, so the gap is large.
Where the system stands
The National Pension Authority runs the UPS, which is voluntary and contributory for citizens aged 18 to 50. It offers four packages: Probash (expatriates), Progati (private-sector employees), Surokkha (self-employed and informal workers) and Somota (low-income citizens). Contributions are collected through banks. Funds are held in state-owned banks and invested mainly in government bonds, and the 2024 investment regulations exclude private enterprises as investment targets.
Two developments change the picture:
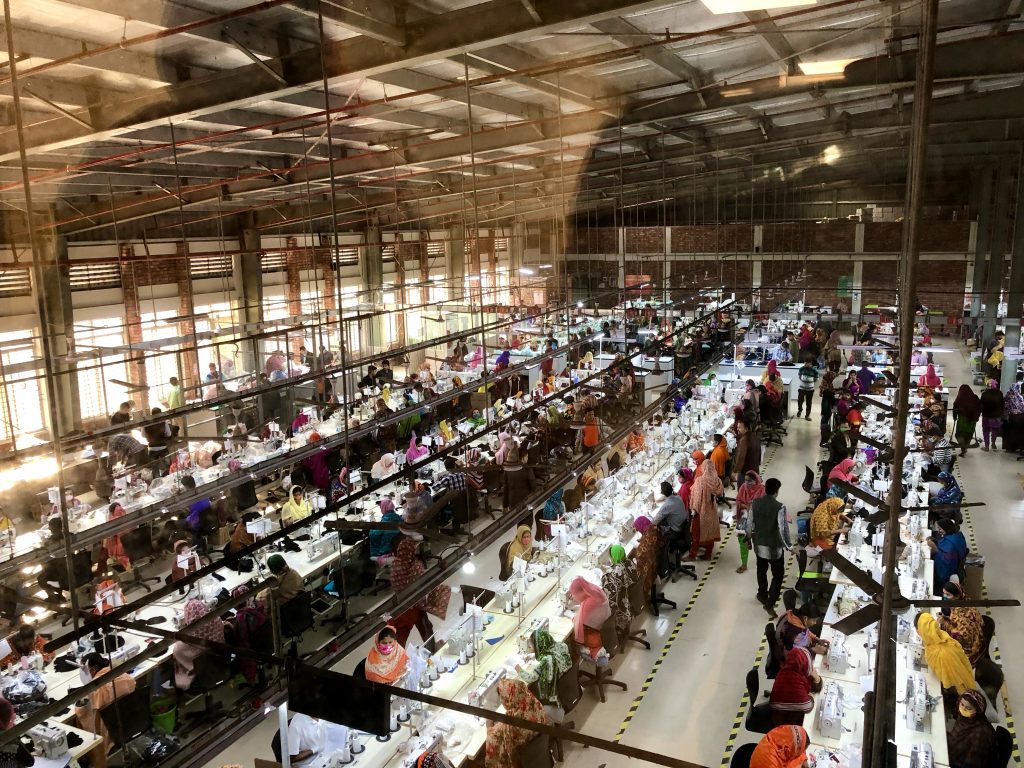
- Mandatory enrolment. The 2026 amendment to the Labour Act requires industrial establishments with more than 100 workers to bring their workforce under the UPS (The Financial Express). BGMEA has already held a discussion with the authority, and its leadership noted that covering nearly five million garment workers brings practical challenges (BGMEA).
- A funded modernisation project. The ADB has committed a US$100 million concessional loan, and a feasibility study is under way (BSS, May 2026), (ADB ref. 59067-001, Ministry of Finance).
The government also says it is working to implement its 2026 election pledge to establish a pension fund (UNB).
What we do not know yet
|
Open question |
Why it matters |
|
Licensing framework and supervisor for private pension funds |
Determines who can operate and under whose oversight |
|
Whether and how foreign entities may participate, including ownership limits |
Decides if a direct presence or a partnership is possible |
|
Tax treatment and profit repatriation |
Central to any business case |
|
Design and timing of the private-sector pension fund |
Defines the commercial opportunity |
| Procurement route and scope of the ADB project |
Determines how advisory firms can take part |
We will update this article as the answers emerge.
Entry options we see
- Technical cooperation: administration, actuarial design, IT systems and investment policy, often donor-funded. Near term, but procurement details are not public.
- Employer-sponsored schemes: advice and administration for large employers, building on the 100-worker rule. Near to medium term.
- Shariah-compliant products: the Finance Minister has signalled openness, but there is no design yet.
- Partnerships and joint ventures: possible once the rules permit.
Frequently asked questions
Can a foreign pension operator get a licence in Bangladesh today? There is no published framework for private pension funds, so the question cannot yet be answered. Watch for the draft law and the ownership rules.
Can private firms take part in the UPS now? Not as fund managers. Banks collect contributions, and the funds are managed within the state framework. Opportunities today lie mainly in advisory and technical work.
Who will supervise private pension funds? No separate supervisor has been announced in the sources we reviewed.
How we can help
Stein & Partners is an independent business and legal advisory firm supporting international companies in Bangladesh. We act as adviser and relationship partner, not as a fund manager, and we are open to discuss client’s positioning and priorities.
Support we can provide includes market-entry strategy and regulatory monitoring, introductions to authorities and employers, licensing and incorporation advice, partner due diligence, and tax and compliance support for employer-based schemes.
-: END :-